

EasyBudget - Budget planning

- 2.55K Reviews
- 4.0
- Downloads
- 500,000+
Our take on EasyBudget - Budget planning from Appgk
I like budget apps that get out of the way. When I want to check whether I can afford a dinner, a subscription, or an unplanned purchase, I do not want to build a complicated financial model first. EasyBudget - Budget planning takes that practical approach. It is a free finance app from Wallet Passes Alliance, designed around monthly budget management rather than investment tracking, banking, or detailed accounting.
After spending time with it, my impression is that its main strength is focus. It encourages me to think in terms of a month, available money, and everyday spending. That makes it approachable for someone who wants more control without learning a full personal-finance system. At the same time, that simplicity creates boundaries. People who need automatic bank synchronization, shared household planning, or deep reports may quickly find it too limited.
The app has a 4.0 average from around 21 thousand ratings and has passed half a million installs, so it is not an obscure experiment. It is rated for Everyone, costs nothing to download, and runs on Android 7.0 or later. I would describe it as a straightforward starting point for monthly budgeting, especially if you prefer entering and reviewing your numbers yourself.
How EasyBudget feels in everyday use
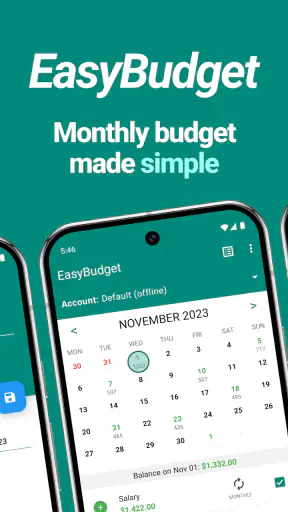
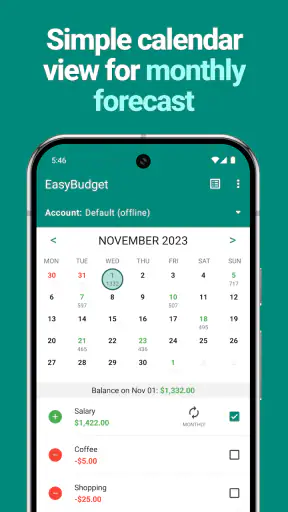
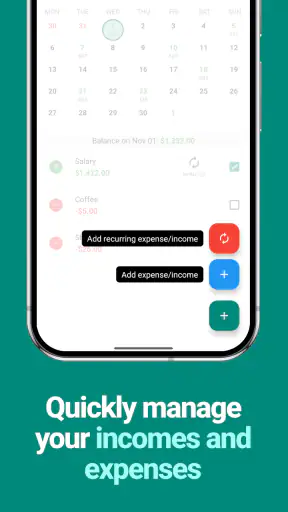
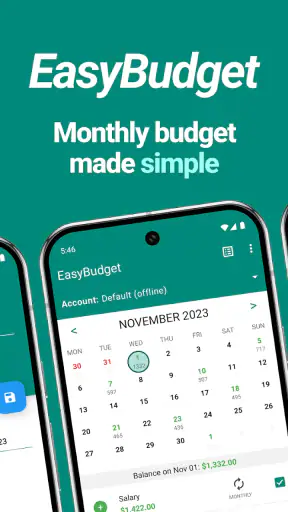
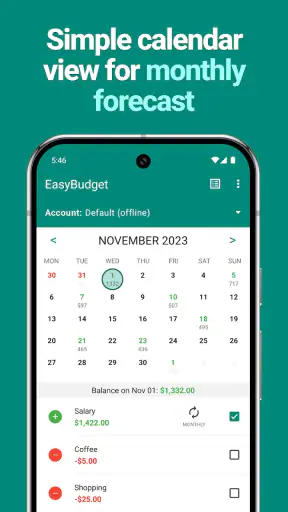
The first useful decision is to treat the app as a spending boundary, not as a complete financial diary. I begin with the money available for the month, account for the expenses I already know are coming, and then use the remaining amount as a guide for flexible spending. That simple sequence is more valuable than it sounds because it turns an abstract goal, such as “spend less,” into a number I can check before making a purchase.
Best Parts of EasyBudget - Budget planning
Things to Keep in Mind About EasyBudget - Budget planning
A realistic example would be a month in which rent, utilities, transport, and groceries are predictable but entertainment is not. I can reserve the essential costs first, then see how much room is left for meals out or a weekend activity. If I check the figure before spending rather than only at the end of the month, the app becomes a small decision-making tool. It does not need to predict my future perfectly to help me pause.
That is where the app feels more useful than a notes document. A note can hold a list of expenses, but it rarely gives the same sense of an active monthly limit. EasyBudget is built around the idea that a budget should be consulted repeatedly. I would keep it close to my normal spending routine, perhaps checking it after payday, before a larger discretionary purchase, and again during the final week of the month.
News and Features Related to EasyBudget - Budget planning

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The interface is best suited to people who want a clear routine instead of a finance dashboard full of charts. I did not approach it expecting investment tools, credit monitoring, or professional bookkeeping. Its place is much narrower: helping me decide how much I can spend while keeping the month in view.
A good fit for manual control
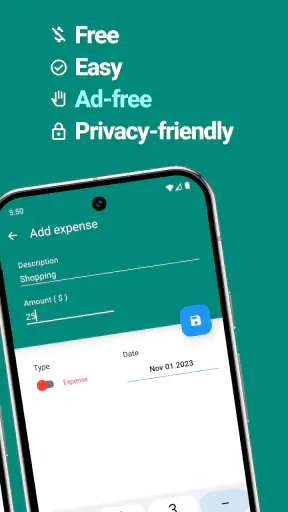
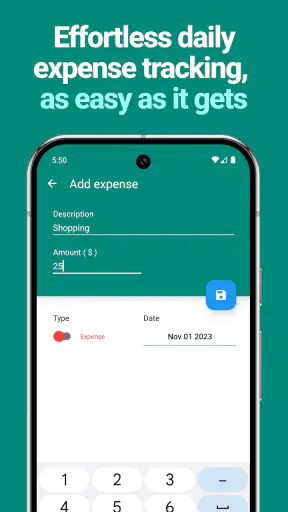
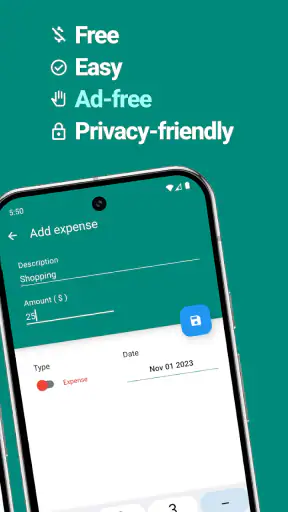
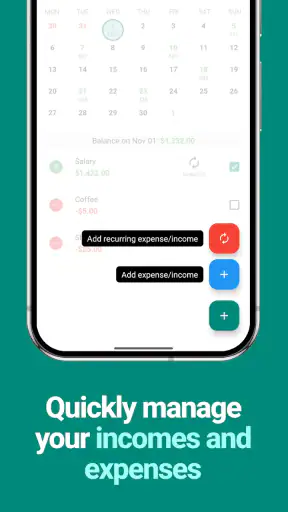
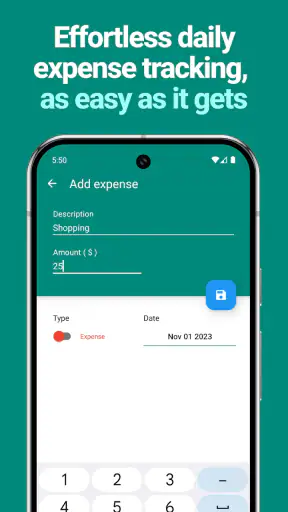
Manual entry is not automatically a weakness. For many users, typing in a purchase makes it more noticeable than an automatic import would. That small moment of recording a coffee, a taxi ride, or an online order can expose habits that disappear when transactions are silently collected in the background.
Don't want to read the full review?
There is a trade-off, though. The system is only as useful as my consistency. If I forget several purchases, the available amount becomes misleading. I would therefore recommend entering expenses at the time they happen, or setting aside a short review at the end of each day. Waiting until the end of the week makes small purchases harder to remember and can give a false impression of control.
A helpful personal rule is to record irregular spending immediately, even when it is inconvenient. A one-off household purchase, a gift, or a medical expense can distort the rest of the month more than several small daily items. Using the app this way makes it a warning system rather than merely a record of what has already gone wrong.
Screenshots
Where the simple design helps
EasyBudget is approachable because it does not require me to understand accounting language before I can begin. Someone moving from mental budgeting or a paper notebook can adopt it without changing their whole financial life. That matters for students, first-time budgeters, people recovering from overspending, and anyone who wants a low-pressure way to build a habit.
I also see value for users with relatively stable income. If money arrives on a predictable schedule and the main goal is to control monthly spending, a focused planner may be preferable to a larger app that asks for bank access or presents more detail than necessary. The lighter approach can make the budget feel personal and manageable.
It is less convincing for irregular income. Freelancers, seasonal workers, and people paid at different times may need a longer cash-flow view than a monthly plan naturally provides. They can still use the app as a short-term spending guide, but they will need to do additional planning elsewhere for taxes, delayed invoices, or uneven income.
What the current version suggests
The current version is 4.1.0, while the app has been available since December 2, 2015. That history tells me the product has had time to settle into its basic purpose rather than being a brand-new budgeting concept. The important point for an existing user is not the version number by itself, but what it says about the app’s role: this is an established, focused utility whose value comes from dependable daily use.
I would not interpret the current release as a reason to expect a completely different product. The app’s appeal is still its direct monthly approach. If you already like that style, updating to the current version is the sensible way to stay with the maintained experience. If you are hoping for a full financial command center, a newer version number should not be mistaken for evidence that the app has moved into that category.
For new users, the current state is easy to understand. You are choosing a budget planner, not a replacement for a bank application. That distinction prevents disappointment. I would use it alongside my normal banking app: the bank remains the source for actual balances and transactions, while EasyBudget acts as the place where I decide how much I want to allocate and spend.
The developer, Wallet Passes Alliance, positions the product in the finance space, and the store summary emphasizes simple monthly planning. In practice, I think that description is most accurate when “simple” means concentrated rather than feature-rich. The app asks me to make a budget and pay attention to it; it does not try to become every financial tool at once.
How the app has evolved for different users
Because the app supports Android 7.0 and later, it remains accessible to people using older compatible phones rather than only recent devices. That can matter if budgeting is something I want to keep separate from my newest phone or if I am helping a family member use an older handset. The Everyone content rating also makes it suitable as a general household finance tool, although the quality of the budget still depends on the user’s choices.
The free entry point is another practical part of its evolution. I can try the workflow without committing money first. There are in-app purchases ranging from under a dollar to just under one hundred dollars per item, so I would review any optional purchase carefully before confirming it. The free starting point is useful for testing whether the monthly method suits me, while the existence of optional purchases means I should not assume every possible capability is included at no cost.
My advice is to spend several weeks judging the habit, not just the first few minutes. A budget app can feel impressive during setup and then become irrelevant if it is awkward during real spending. With EasyBudget, the important test is whether I still open it when the month becomes busy, whether I can update it without friction, and whether its number changes my decisions.
What changes mean for existing users
Someone who has used the app for a long time will probably care most about continuity. Existing budgets and routines are valuable precisely because they reduce mental effort. Before making a major change to how I use any finance app, I would note my current monthly figures and make sure I understand where my active plan sits. That is not a criticism of this particular app; it is a sensible precaution whenever personal financial records are involved.
For an established user, the strongest benefit is familiarity. Once the monthly workflow becomes automatic, I do not need to reconsider categories or rebuild a complicated system every time I open the app. The downside is that a familiar simple tool can also hide a stale routine. If I keep entering the same estimates without comparing them with real spending, the app may preserve my assumptions instead of improving them.
I would use each new month as a small review point. Look at which expenses repeatedly exceed expectations, which categories are too broad to be useful, and which costs should be treated as fixed rather than flexible. This turns EasyBudget into a learning tool. The app supplies the structure, but I have to adjust the plan when my life changes.
Limitations I would consider before installing
The main limitation is the amount of manual responsibility involved. If I want automatic transaction collection, the convenience of bank connections, or instant categorization, this is probably not the right choice. A more automated finance app will save time, although it may also require more setup, account access, and trust. EasyBudget is better for someone who intentionally wants to enter the numbers and remain aware of them.
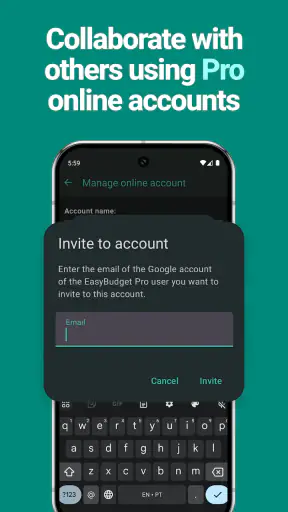
It also may not satisfy couples or families who need a shared budget with clearly separated responsibilities. A single monthly plan can still help a household discuss spending, but it does not replace a coordinated system where multiple people update the same financial picture. For that use case, a collaborative alternative would likely be more practical.
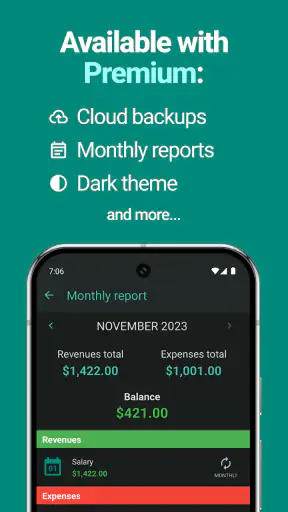
Detailed analysis is another possible gap. If I want extensive historical comparisons, elaborate category reports, debt payoff projections, investment performance, or tax-oriented records, I would look elsewhere. EasyBudget’s strength is that it keeps the central question visible: how much can I spend within this month? That focus is helpful until my financial questions become more complex.
There is also a behavioral limitation that no interface can fully solve. A budget can show that I have room to spend, but it cannot know whether that money should be saved for an upcoming annual bill. I need to reserve irregular expenses myself. A useful workaround is to treat known yearly costs as monthly commitments by dividing them into smaller amounts and setting that money aside mentally or in another account. Without this step, the monthly figure can look healthier than my real finances are.
Three practical habits that make it more useful
First, I would create the monthly plan using actual recent spending rather than an idealized version of myself. If I usually spend more on groceries or transport than I wish I did, starting with an unrealistically low figure makes the app feel like a judge instead of a guide. I can reduce the amount gradually after I have identified what causes the overspend.
Second, I would separate predictable commitments from flexible choices. Rent and a regular bill should not compete mentally with a spontaneous purchase. Even if the app’s structure is simple, I can preserve that distinction in the way I organize my planning. This makes the remaining amount more honest and helps me see which decisions are genuinely optional.
Third, I would use the remaining balance as a pacing signal, not permission to spend everything. If I am halfway through the month with most of the flexible budget untouched, that does not automatically mean I should use it. I may have a larger expense ahead. This is a subtle but important trade-off: a budget is most useful when it supports restraint as well as spending.
A fourth habit is especially useful for people who make many small card payments. I would review the plan before shopping online, because small digital purchases are easy to overlook. Recording them immediately creates a more accurate picture than relying on memory. This is one area where a simple manual app can be surprisingly effective, provided I respect the routine.
Who should choose it, and who should skip it
I would recommend EasyBudget to someone who wants a gentle first step into personal finance, prefers manual control, and mainly needs a monthly spending framework. It is also a reasonable option for a user who does not want to connect financial accounts and is willing to maintain the plan directly. The free download makes experimentation easy, and the broad device compatibility lowers the barrier to trying it.
I would skip it if my priority is automation, shared real-time budgeting, or advanced financial analysis. I would also be cautious if I know I will not record purchases consistently. In that situation, a bank-linked tool may produce a more complete record, even if it demands more configuration. Choosing the simpler app only works when its simplicity matches my behavior.
Compared with a spreadsheet, EasyBudget should feel less intimidating and more convenient for a quick monthly check, while a spreadsheet offers greater flexibility and custom calculations. Compared with a paper notebook, it is easier to revise and consult during the day, but it may feel less tangible. Compared with an automated finance platform, it gives me more deliberate control but less passive visibility. Those are meaningful differences, not merely design preferences.
What I would watch next
When I look at the future of this app, I would pay attention to whether it preserves its straightforward monthly identity while reducing the small annoyances of manual upkeep. Better clarity around entering expenses, reviewing a month, and understanding optional purchases would matter more to me than a long list of unrelated features.
I would also watch how well the app serves people whose financial lives are changing. A beginner may start with one monthly figure, then later need irregular income planning, savings targets, or more detailed categories. The best evolution would help users grow without turning the original simple workflow into a crowded dashboard. Until then, I would treat it as a focused tool and pair it with another method when my needs expand.
My final view is positive but specific. EasyBudget is not a complete financial ecosystem, and I would not recommend pretending that it is. It is a practical monthly budgeting companion for people who want to see their spending limit, enter their own expenses, and build awareness through repetition. The best reason to use it is not the number of features, but the chance to make one clear spending habit stick.
For me, that makes the app worth trying when the goal is simple: plan the month, check the plan before spending, and adjust honestly when reality differs from the estimate. If that sounds like the kind of control you want, the current release is a sensible place to start. If you need automatic data, shared finances, or professional-level reporting, I would choose a more specialized alternative instead.
EasyBudget - Budget planning FAQ
What is EasyBudget - Budget planning, and who is it designed for?
EasyBudget - Budget planning is a personal finance app designed to help users organize income, expenses, and spending limits in one place. After reviewing its budgeting workflow, it appears most useful for people who want a straightforward overview of their finances without relying on complicated spreadsheets. It can suit beginners, students, families, and anyone trying to build more consistent money-management habits.
How does EasyBudget help users create and follow a budget?
The app lets you plan a budget by recording your expected income and assigning spending amounts to different categories, such as food, transportation, bills, shopping, or entertainment. As expenses are entered, you can compare actual spending with your plan and identify areas that may need adjustment. This makes it easier to monitor daily decisions instead of waiting until the end of the month.
Is EasyBudget suitable for tracking irregular income and expenses?
EasyBudget can be useful for users whose finances change from month to month, although the experience may require more manual organization than a specialized accounting service. Freelancers, part-time workers, and households with occasional expenses can enter income and payments as they occur, then adapt their budget accordingly. Users should regularly update entries so the displayed balance remains reliable.
Does EasyBudget require an internet connection or access to bank accounts?
Budget apps differ in how they handle synchronization and financial connections, so users should check the current permissions and app-store description before downloading. EasyBudget is primarily focused on manual budget planning and expense organization rather than replacing a bank application. If you prefer not to connect financial accounts, entering transactions yourself can provide greater control over what information is stored.
Is EasyBudget safe to use for personal financial information?
Before adding sensitive details, review EasyBudget’s privacy policy, requested permissions, and data-handling practices in the official Android or iOS listing. A budgeting app may contain information about income, bills, and spending habits, so protecting your device with a passcode or biometric lock is recommended. Avoid entering banking passwords, card PINs, or other credentials unless the app clearly explains secure support for them.













